Share structure describes how a company’s equity is divided across the current share base, possible future shares, tradable float, treasury stock, and ownership rights. For investors, it helps separate questions about current ownership, dilution risk, market availability, and per-share economics.
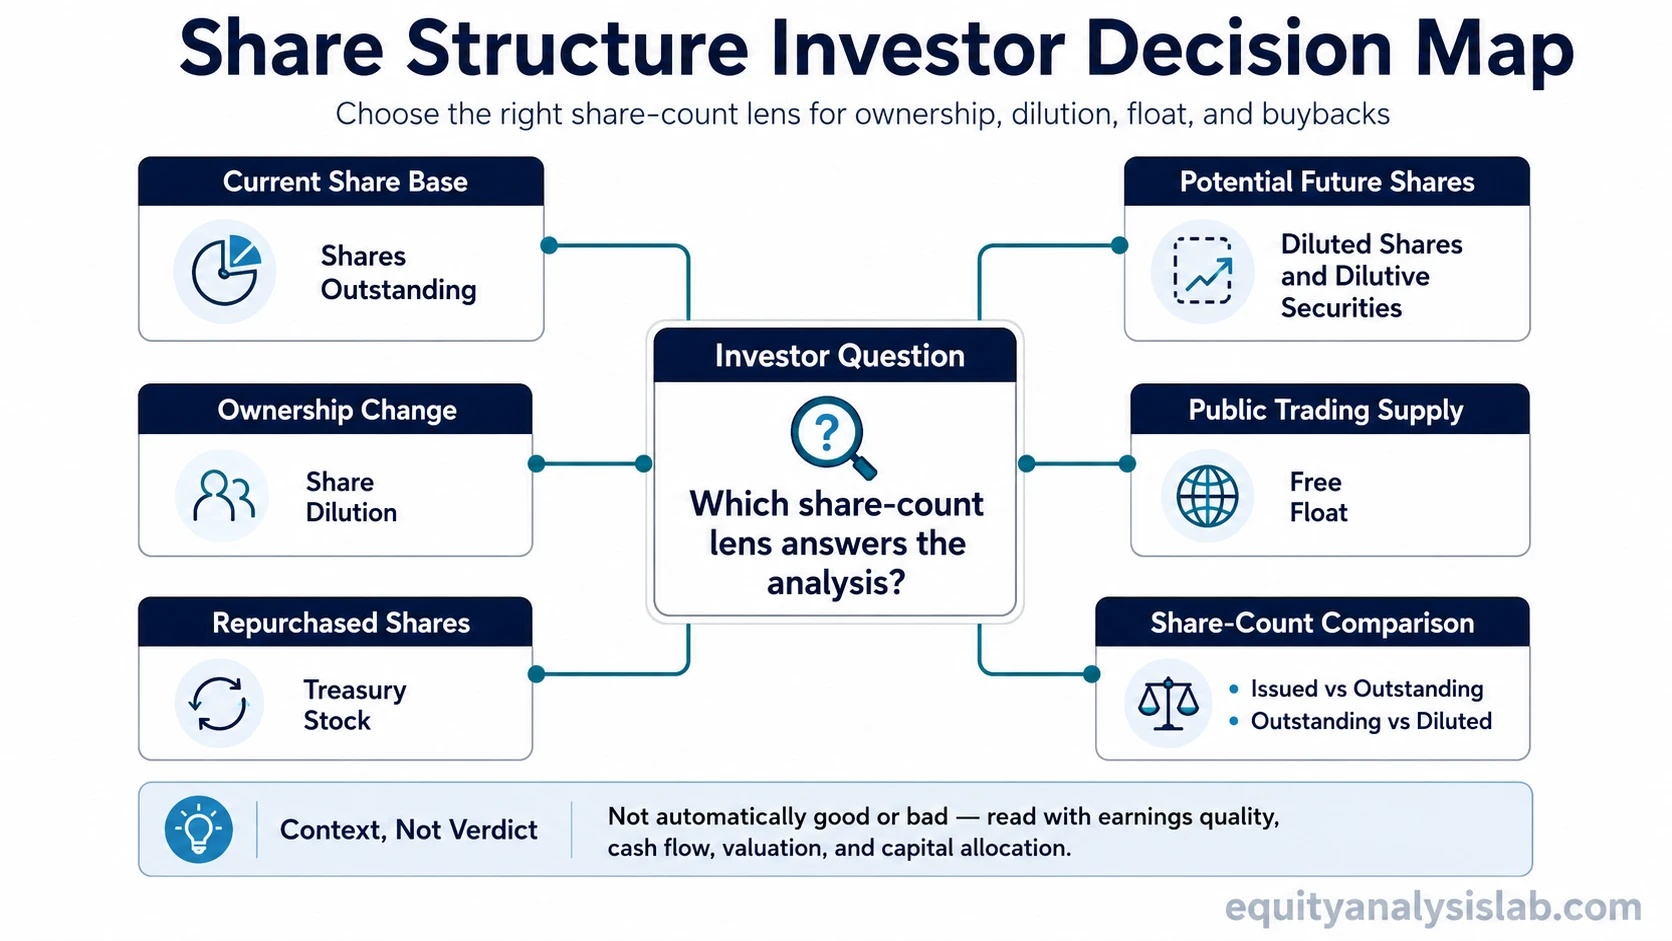
A useful review starts with the question being asked: current ownership, possible future dilution, public trading supply, repurchased shares, or the right share-count comparison. Each question points to a different metric or comparison.
Share Structure Concepts and Where to Start
Current ownership, potential dilution, tradable supply, repurchased shares, and share-count comparisons answer different investor questions. The table routes each question to the page that owns it.
| Investor question | Share-structure concept | What it helps clarify | Start here |
|---|---|---|---|
| How many shares currently represent the company’s equity base? | Current share base | The number of company shares currently held by shareholders, before considering possible future dilution. | Shares outstanding |
| What share count should be considered when eligible potential dilution matters? | Dilution-adjusted share count | The broader share-count lens used when eligible potential dilution matters under the relevant reporting or analytical method. | Diluted shares outstanding |
| Which instruments could increase the future share count? | Potential future-share instruments | The securities or contracts that may become common shares and affect future ownership or per-share analysis. | Dilutive securities |
| How can a larger share base reduce existing ownership or change per-share results? | Ownership dilution | The effect of a larger share base on ownership percentage and per-share measures. | Share dilution |
| How much of the outstanding share base is available for public trading? | Tradable share supply | The portion of outstanding shares treated as available to public investors under the relevant float methodology. | Free float |
| What happens to shares a company has repurchased and now holds? | Repurchased shares | How company-held shares differ from shares held by outside shareholders. | Treasury stock |
| Why are issued shares and outstanding shares not always the same? | Issued vs outstanding | The difference between shares created by the company and shares currently held outside the company. | Issued shares vs outstanding shares |
| When should an investor compare the current share base with a diluted share-count measure? | Outstanding vs diluted | The distinction between current shares outstanding and a measure that reflects eligible dilution. | Shares outstanding vs diluted shares outstanding |
| How does the full ownership base differ from the publicly tradable subset? | Outstanding vs free float | The distinction between total shares outstanding and the subset normally treated as available for public trading. | Shares outstanding vs free float |
A Simple Share Structure Reading Example
Company A can have a stable share count and a relatively small public float because a large part of the outstanding share base is closely held. Company B can have a broader public float while its share count rises because it keeps issuing equity.
The first case pushes the review toward tradable supply and ownership concentration. The second pushes it toward dilution and per-share economics. The same share-structure label does not answer both questions.
What Share Structure Does Not Explain by Itself
A stable share count cannot offset weak cash flow, poor capital allocation, an overstretched valuation, or a fragile business model. A more complex share structure is not automatically negative either. The share base has to be read alongside the economics behind issuance, repurchases, ownership changes, and per-share results.
Scope of This Share Structure Hub
This hub stays focused on investor questions about the current share base, potential dilution, tradable supply, repurchased shares, and the denominator used in per-share analysis. Share classes and voting rights matter when they change control or governance, but a full legal share-class analysis sits outside this investor-focused route map.